Should you buy Ulta Beauty stock? (January 2024)
Up Next
8 videos
TSMC Is Reporting Lower Revenue But It Still Looks Like A Buy
July 26th, 2023
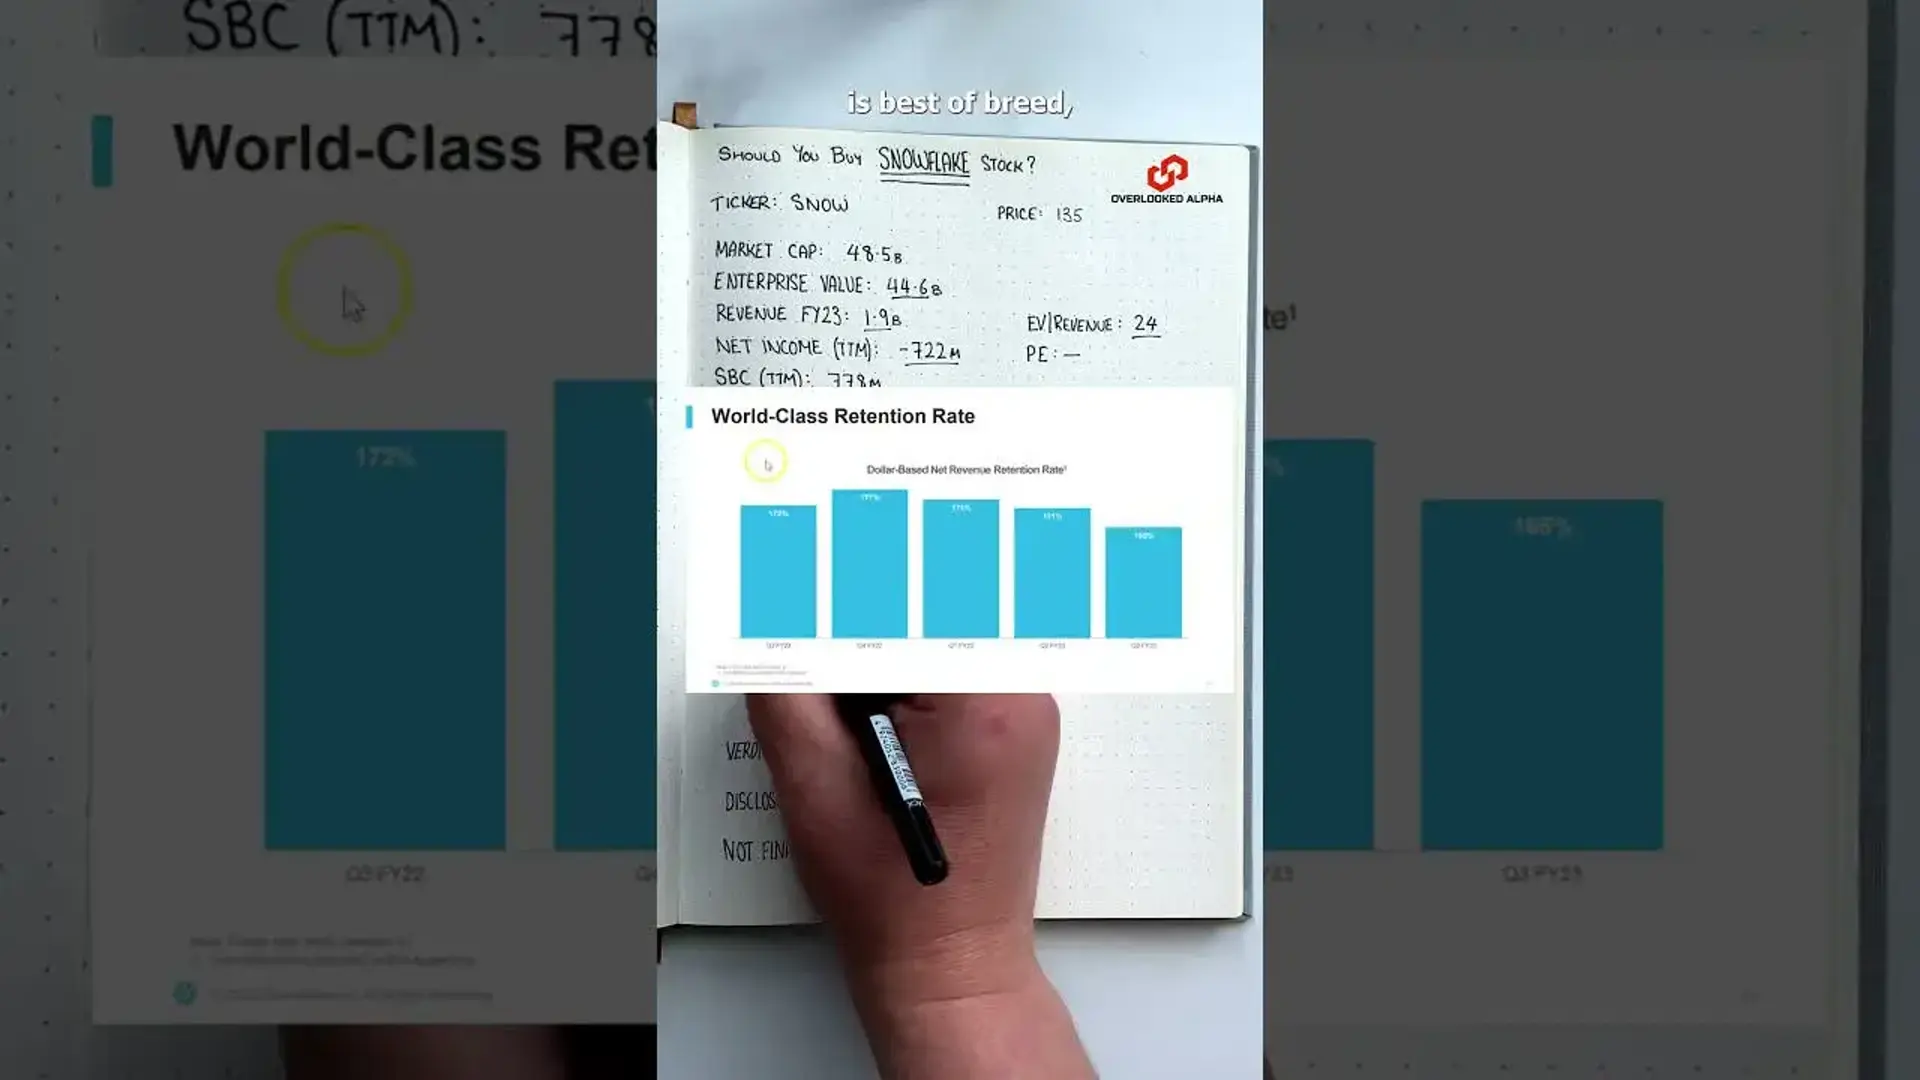
Snowflake stock analysis #shorts
December 1st, 2022
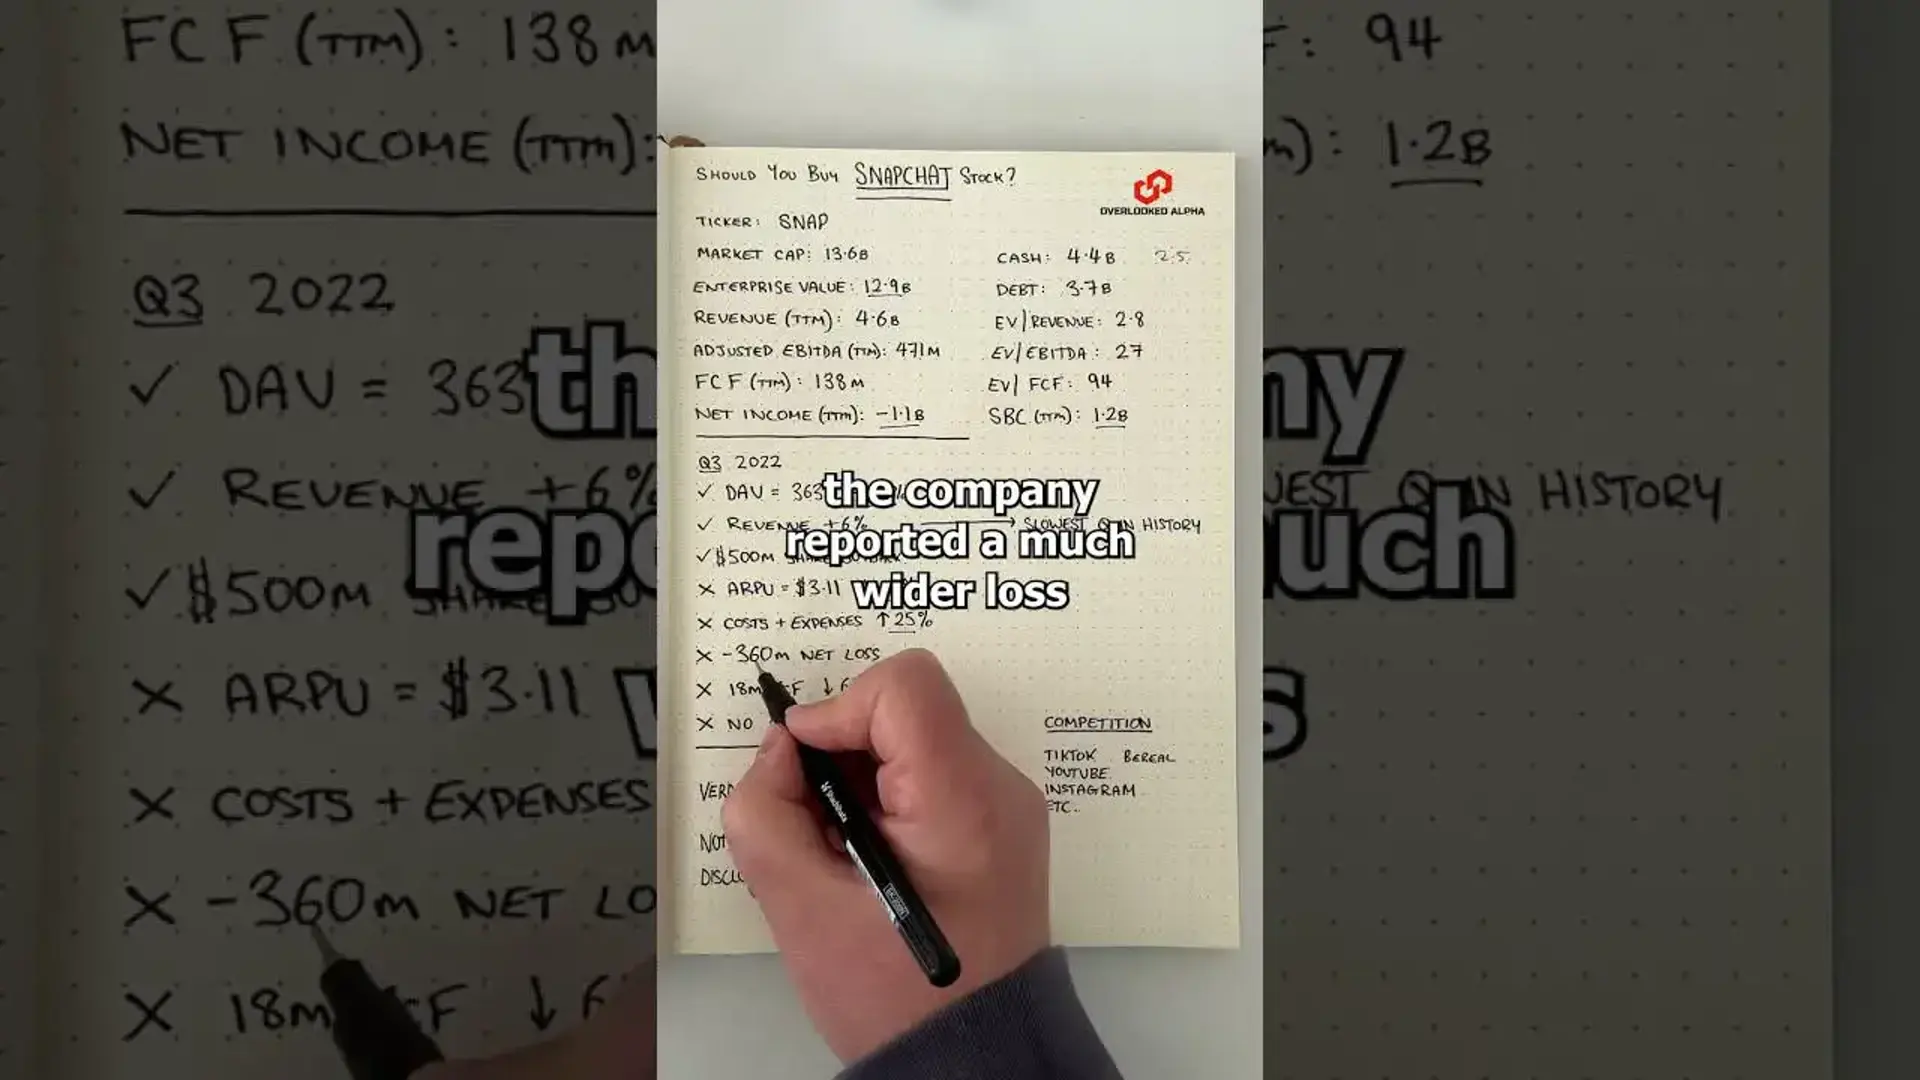
Snapchat earnings analysis #shorts
October 23rd, 2022
Everything Is Overvalued
October 15th, 2024
3 Stocks To Avoid In 2025
December 29th, 2024

Should you buy Uranium stocks? (August 2023)
August 6th, 2023
Should you buy Uranium stocks? (August 2023)
August 6th, 2023

How to follow famous investors (free tool) #shorts
April 26th, 2023
Newsletter subs get it first: https://www.3minutebreakdowns.com Ulta stock analysis. Ticker: $ULTA Ulta Beauty is the largest beauty retailer in the US with around 1400 stores. At the current price, the company has a market cap of 23 billion dollars with 122 million of cash on its balance sheet and no debt. Revenue over the last 12 months totals 11 billion, with 1.2 billion of net income and 1.9 billion of ebitda. So Ulta stock is now valued at just over 2 times revenue, and 19 times earnings. That valuation seems reasonable but there are signs that the business is slowing down. Revenue growth should come in at 9% this year which is half last year’s figure and in May the stock dropped 28% after the company posted lower profit margins. Inflation has clearly hurt consumer demand with the average sale per customer dropping by 1.5% in the first quarter. However, it’s worth putting those numbers into perspective. Skin care and beauty products saw huge demand following the pandemic. ULTA grew its revenues 40% in 2022 and 18% in 2023. So some normalization is to be expected. #investing #3mb #stockstobuy #stockstobuynow